Sectors

    Property, fire & business interruption

    For factories and warehouses, a fire or flood damages more than property: it can stop production for weeks. Most disputes come from under-insurance and how business interruption losses are calculated.

    • Free consultation
    • Same-day response
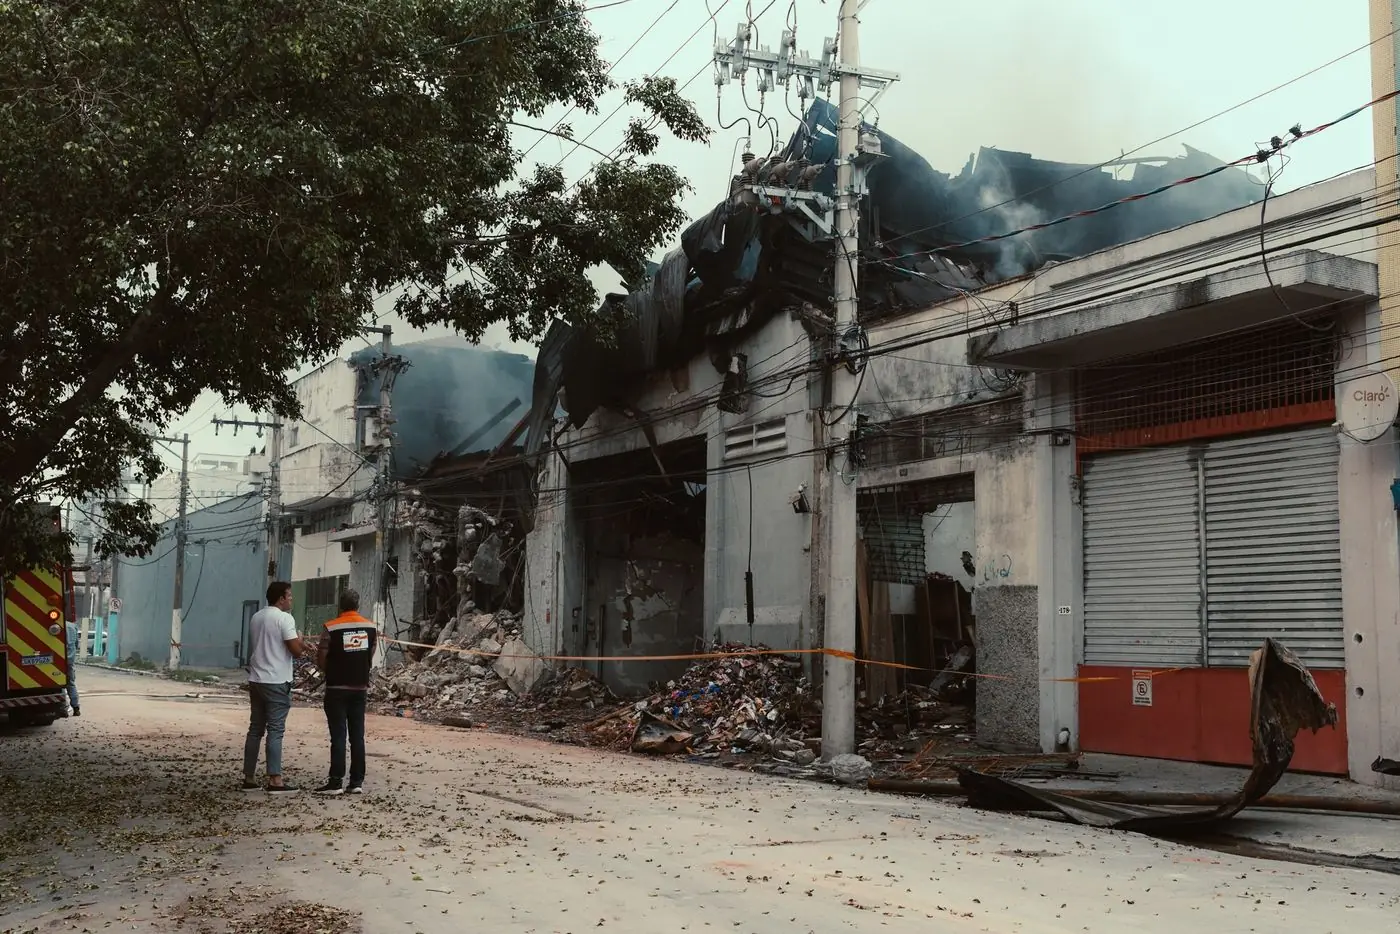
    Site after a warehouse fire

    Typical exposures

    1. 1

      Fire and explosion

      Electrical faults, hot work, combustible storage and fire spreading from neighbours.

    2. 2

      Storm and flood

      Flooded warehouses, damaged machinery and stock in low-lying areas.

    3. 3

      Machinery breakdown

      Failure of critical equipment stopping a whole line.

    4. 4

      Business interruption

      Lost revenue, fixed costs still payable, extra costs to keep orders going.

    Common claim pitfalls

    • Under-insurance

      A sum insured below actual value means the claim is reduced proportionally.

    • Cannot prove stock value

      Stock records not up to date, or destroyed in the same incident.

    • Gross profit miscalculated

      Accounting figures not prepared on the BI policy's definitions.

    Common insurance covers

    • Compulsory fire insurance and property all risks
    • Business interruption
    • Machinery breakdown
    • Stock insurance on a declaration basis

    Illustrative cases

    Warehouse · Flood

    Payout reduced for under-insurance

    Situation
    A finished-goods warehouse flooded after a storm. Stock on the day of loss was far above the sum insured declared at the start of the year.
    Issue
    The insurer proposed applying average, significantly reducing the settlement.
    How we help
    We checked the stock declaration clauses, compiled monthly records to prove actual values and proposed a calculation consistent with the policy.
    What to do beforehand
    Where stock fluctuates seasonally, use a periodic declaration basis rather than a fixed annual sum insured.
    Factory · Business interruption

    BI cover in place but no way to calculate it

    Situation
    A main switchboard fire stopped production for several weeks. The policy included business interruption cover.
    Issue
    The company had no gross profit figures on the policy's definition; the first estimate was far below the actual loss.
    How we help
    We built monthly revenue and output figures, identified fixed costs still payable and extra costs to keep operating, presented on the policy's definitions.
    What to do beforehand
    When buying BI cover, set the sum insured with your accountant using the policy's own definition of gross profit.

    Illustrative scenarios drawn from common market cases, not the file of a specific client.

    Your specialists

    • Truong Ngoc Trac

      Chief Operating Officer

      Marine engineer · Surveying & marine insurance

    • Le Hong Hung

      Specialist

      Legal · 10+ years managing claims

    • Tran Thien Hai

      Specialist

      Civil engineer · Construction insurance

    Related articles

    Talk to a specialist

    Send us your policy or a description of what happened and the relevant specialist will reply the same day. Advice is free; fees apply only once you decide to engage our services.