Insurance programme
Under-insurance: why an insured loss can still be paid short
Declaring a low sum insured to save premium can cost you a large share of a claim, even for a small loss.
Fo4U team · · 4 min read
Property insurance assumes the sum insured reflects the true value of the property. When it is lower, most policies apply proportional settlement, known as the average or under-insurance clause.
How it is calculated
Claim payment = Loss × (Sum insured ÷ Actual value at risk), before the deductible.
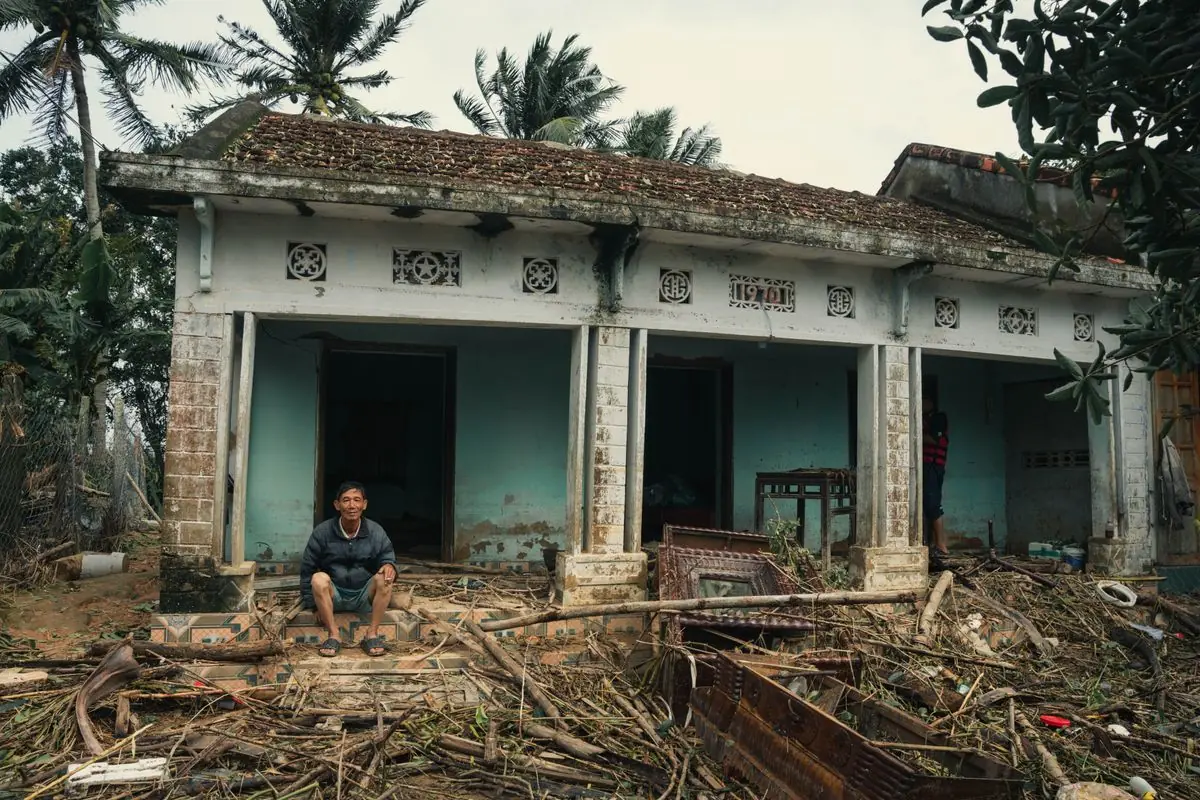
Example: a warehouse is insured for VND 10 billion, but its actual value at the time of loss is VND 20 billion. A flood causes VND 4 billion of damage. The proportional settlement is 4 × 10/20 = VND 2 billion. The business bears half of the loss, even though the loss was far below the sum insured.
Where it usually happens
- Stock rises sharply in peak season while the sum insured is fixed for the year.
- Machinery declared at depreciated book value while the policy pays on a new replacement basis.
- A plant expands or adds equipment without endorsing the policy.
How to avoid it
- Confirm the basis of value the policy uses (reinstatement or indemnity) and declare on that basis.
- For fluctuating stock, use a declaration clause: insure a maximum, declare actual values monthly or quarterly, adjust premium at the end.
- Review sums insured after major investments and before every renewal.
- Ask whether the policy allows a margin of under-insurance before average applies.
General guidance only. Your actual entitlement depends on your policy and the facts of each case.